Where the Next Frontier Actually Is: A Due Diligence Framework for Second-Tier Market Entry
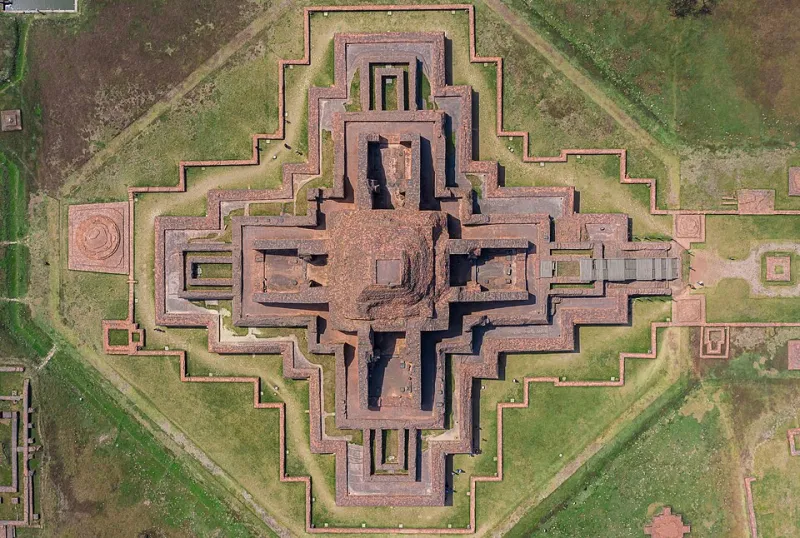
Photo: Md. Ahsanul Haque Nayem, CC BY-SA 4.0, via Wikimedia Commons
The math is no longer subtle. Prime commercial real estate in Singapore, London, and Dubai commands entry costs that put meaningful overseas expansion out of reach for most American mid-market firms. Meanwhile, the corridors those hubs dominate have grown crowded — with institutional capital, with competing distributors, with identical market-entry playbooks. It is little wonder that a growing cohort of US investors and operators has begun looking one ring outward, toward second-tier cities where land is cheaper, incentives are richer, and first-mover advantages remain genuinely available.
But the tier-two thesis carries a well-earned warning label. For every secondary city that matured into a regional engine, dozens of others absorbed foreign capital without ever delivering returns. The question is not whether tier-two markets can outperform gateways — sometimes they clearly can. The question is how an American firm distinguishes the next emerging anchor from a costly detour.
Three Tests That Separate Signal From Noise
Regulatory maturity. A tier-two market is only as investable as the legal machinery behind it. Sophisticated entrants look past headline growth rates and examine whether commercial courts function, whether contracts are enforced in practice rather than on paper, and whether foreign ownership rules are stable or subject to quiet revision. A city can post double-digit GDP growth and still be a jurisdiction where a minority shareholder has no realistic recourse. US investors should demand evidence: arbitral track records, the pace of business registration, and how the last dispute between a foreign investor and a local counterparty actually resolved.
Infrastructure pipelines, not promises. Every ambitious secondary city has a master plan. The differentiator is what has already broken ground — and who is financing it. Ports with committed throughput, freight rail connections to the national backbone, power capacity that does not require private generation as a default: these are markers that a location can physically support a supply chain, not just a pitch deck. Investors should be skeptical of infrastructure that exists only in renderings, particularly when the financing structure behind it is unclear.
A real partner ecosystem. Perhaps the most reliable indicator of a viable tier-two market is whether credible local operators — accountants, customs brokers, logistics firms, legal counsel with international credentials — have already built practices there. Where that ecosystem is thin, every operational function becomes a bespoke project, and every project carries hidden cost and delay. Where it is dense, entry timelines compress dramatically.
The Presence Premium
Even a thorough desk review cannot substitute for what seasoned operators call the presence premium: the informational advantage that comes from having trusted, embedded representation in the market itself. Tier-two cities run on relationships and reputation in ways that gateway markets, with their formalized institutions, do not. Pricing signals, regulatory wind direction, the true standing of a prospective joint-venture partner — these are legible to someone standing in the market, and nearly invisible from a conference room in Chicago or Dallas.
This is precisely where the gap between successful tier-two entrants and expensive failures tends to open. Firms that treat a secondary market as a scaled-down version of a gateway entry — same playbook, smaller budget — routinely underestimate how much local mediation matters. Those that anchor their entry with established on-the-ground partners consistently report faster licensing, better supplier terms, and earlier warning when conditions shift.
Noor Safi Group has built its practice around this exact conviction: that durable cross-border ventures are constructed on verified local intelligence, not exported assumptions. For American firms evaluating second-tier opportunities, that translates into structured market assessments, vetted partner introductions, and operational oversight that continues well after the ribbon-cutting.
A Disciplined Path In
The tier-two opportunity is real, but it rewards patience over enthusiasm. A prudent sequence for US mid-market investors looks like this: validate regulatory enforceability before committing capital; verify infrastructure against physical reality; map the local partner ecosystem before selecting one; and secure embedded representation that reports to you, not to the market's cheerleaders. Entering with an option to scale — rather than a bet-the-company commitment — preserves the flexibility that makes secondary markets attractive in the first place.
Gateway cities will always have their place. But for American firms willing to do the diligence, the next decade of outsized international returns is more likely to be written in second-tier cities — by the investors who arrived with a framework, a local anchor, and the discipline to walk away when the numbers did not hold.